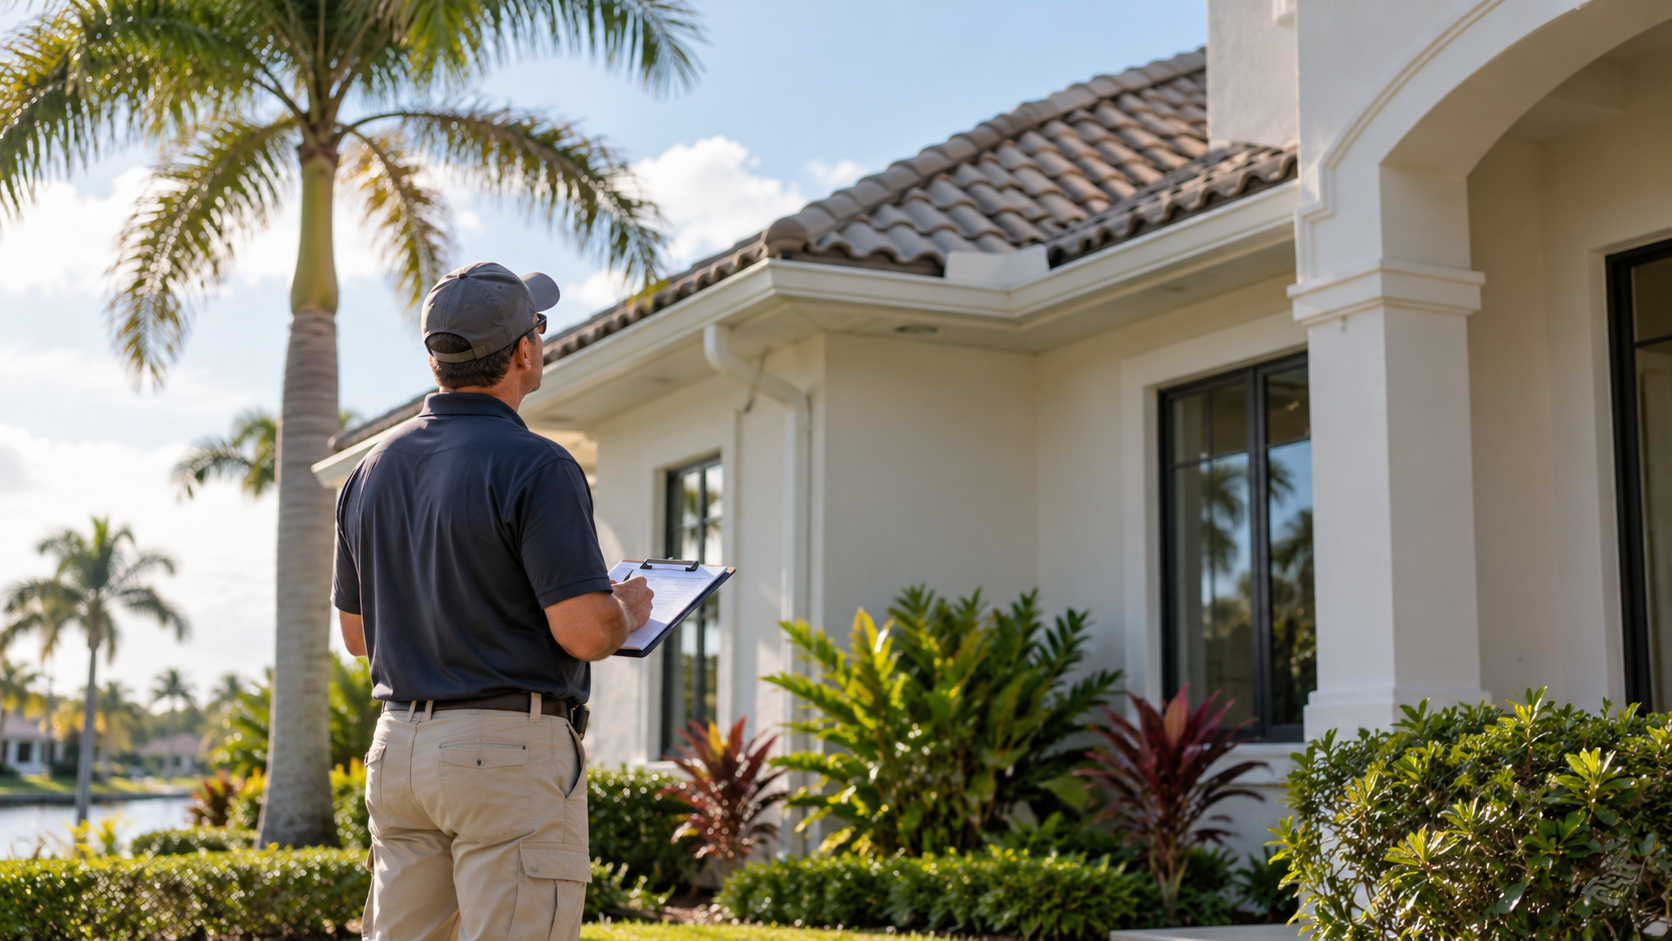
Florida homebuyers may encounter two different insurance-related inspections: a wind mitigation inspection and a 4-point inspection. They serve different purposes. A wind mitigation inspection documents features that can reduce wind damage and may support insurance discounts if the insurer approves them. A 4-point inspection commonly reviews the roof, electrical, plumbing and heating or cooling systems when an insurer requests information about an existing home. Requirements vary by insurer and property.
What does a wind mitigation inspection review?
A qualified inspector documents hurricane-protection and construction features on Florida’s Uniform Mitigation Verification Inspection Form. The form and supporting photos help the insurance company evaluate whether the home may qualify for wind-related premium credits. The insurer determines eligibility; an inspection does not guarantee a discount or coverage.
Florida’s Department of Financial Services notes that a revised form applies to inspections on or after April 1, 2026, and that a completed form can remain valid for up to five years if the home has not materially changed and the information is accurate. Confirm current requirements with your insurer and inspector. See the Florida DFS mitigation forms and inspection guidance.
What is a 4-point inspection?
A 4-point report focuses on four major systems: roof, electrical, plumbing, and heating or air conditioning. An insurer may request it when evaluating an older home or a specific risk. It is not the same as a full home inspection and does not replace a buyer’s broader property evaluation. Ask the insurance agent what form, age limits, photographs or repairs the carrier requires.
How should Boca Raton buyers prepare?
Ask the insurance agent early which inspections and documents are needed for a quote or application.
Request available records for roof replacement, electrical updates, plumbing work, HVAC service and hurricane protection.
Have the appropriate qualified inspector document the property; do not assume a seller’s old report will satisfy a carrier.
Review repair recommendations with relevant licensed professionals and obtain insurance terms in writing.
Compare the report with the standard inspection and any property-specific evaluations during your contract period.
Frequently asked questions
Does a wind mitigation report guarantee lower insurance premiums?
No. It documents features for the insurer’s review. The carrier decides whether credits apply and what coverage and premium it will offer.
Can one inspection replace the other?
No. The inspections have different scopes and forms. Ask the carrier which reports it needs.
Should I order these inspections before making an offer?
Discuss timing and requirements with your insurance agent and real estate professional. The contract period may be the practical time to collect property-specific reports.
Include insurance review in your home search
Insurance availability and cost are part of the ownership budget. Read our Boca Raton buyer’s guide and closing-cost guide, then contact Jennifer Susanne Sommers at Sotheby’s International Realty to discuss your next steps. Visit Florida DFS homeowners insurance overview for consumer information.
Connect